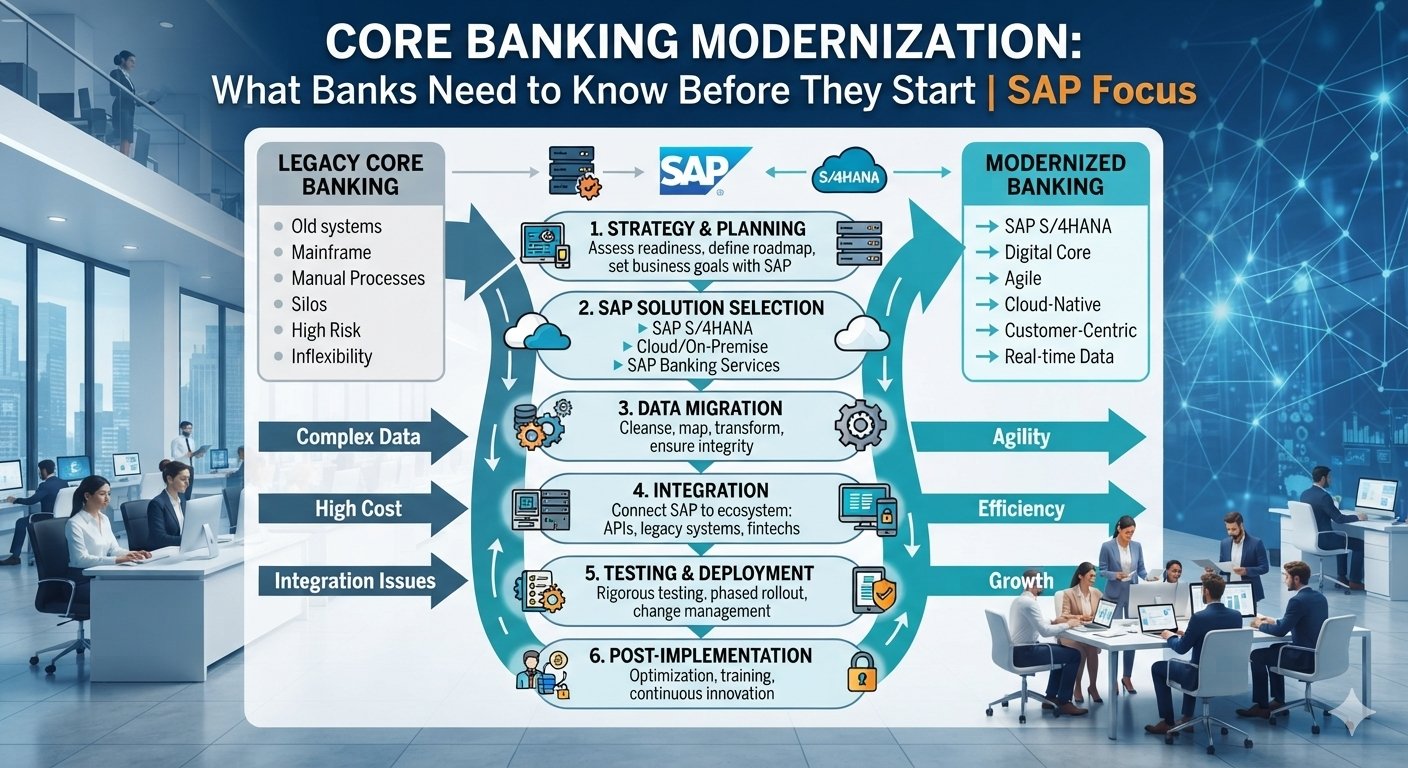
Customers today expect to open an account in minutes, get a loan decision the same day and see every transaction the moment it happens. Yet many banks still run on core systems designed decades ago, patched and extended until every change becomes slow and expensive. Modernizing the core is no longer optional for banks that want to compete.
Signs your core banking system is holding you back
- Launching a new product takes months instead of weeks.
- Batch processing means customers and staff wait for overnight updates.
- Connecting fintech partners or new digital channels needs costly custom work.
- Compliance reporting relies on spreadsheets and manual checks.
- Few people still understand the old system well enough to change it safely.
What a modern core banking platform brings
A modern core is built for real-time processing, open APIs and configuration rather than custom code. That means products can be designed and launched faster, customers get instant updates across channels, and partners connect through standard interfaces.
For banks offering Shariah-compliant products, a dedicated Islamic core banking solution handles profit sharing, Murabaha, Ijarah and other structures natively, instead of forcing them into a conventional model.
Three ways to modernize, with less risk
1. Replace the core
A full replacement gives the biggest long-term benefit, but it is the largest project. It works best with strong governance and a phased migration of products and customers.
2. Hollow out the core
Move products and services to the new platform one at a time, while the old core keeps running. Risk stays low and value arrives early.
3. Wrap and extend
Add an API layer and modern services around the existing core. It is the fastest way to open new digital channels, and a good first step toward a later replacement.
Beyond the core: lending and fraud
Modernization is also the moment to improve the journeys customers feel most.
- Loan origination software digitizes the journey from application and credit assessment to approval and disbursement, cutting decision times from weeks to hours.
- Fraud management uses rules, analytics and machine learning to spot suspicious activity across channels in real time, before money leaves the bank.
- Retail management software gives branches and relationship managers one view of every customer.
How Data ETL helps banks modernize
We work with banks and financial institutions to plan, implement and support core banking, Islamic banking, lending and fraud platforms. Our teams in Dallas and Dhaka combine banking domain knowledge with strong integration skills, so new platforms connect cleanly with the systems you already run.
Planning a modernization program? Explore our banking solutions or talk to our team about where to start.